A Serious Claim Changes the Calculation
A routine drive home can become a financial calculation after one serious accident. Medical bills, lost wages, legal costs, and a court judgment may reach far beyond the limits listed on an auto policy. The same shift can happen at home when a guest suffers a major injury or a household member causes harm elsewhere.
At that point, the question is not simply whether insurance exists. It is whether the available liability limit matches the assets, future income, and activities exposed to a claim. A policy with a modest premium may protect only the first layer of loss, leaving the remaining balance attached to savings, property, or earnings. That possibility makes umbrella insurance worth examining, even before deciding whether its added cost is justified.
The First Surprise: Your Limits May Disappear Quickly
The shortfall often appears faster than expected. A serious auto claim can involve emergency treatment, rehabilitation, months of missed work, and a lawsuit that takes years to resolve. If the policy limit is $250,000 or $500,000, that amount may cover only part of the medical and legal costs before a settlement or judgment is reached. Once the insurer pays its maximum, the remaining exposure does not disappear; it shifts to the person responsible.
Homeowners coverage can create the same surprise. A fall on an icy walkway, an injury at a pool, or damage caused by a household member may produce costs that are difficult to estimate early in the claim. Legal defense may be included within the liability limit, reducing the amount available for the final payment. Higher limits can help, but increasing them may still leave a gap when property, investments, business interests, or future earnings are substantial. The practical review starts with the limits already in place, then tests how quickly one severe event could consume them.
Which Risks Are You Actually Carrying?
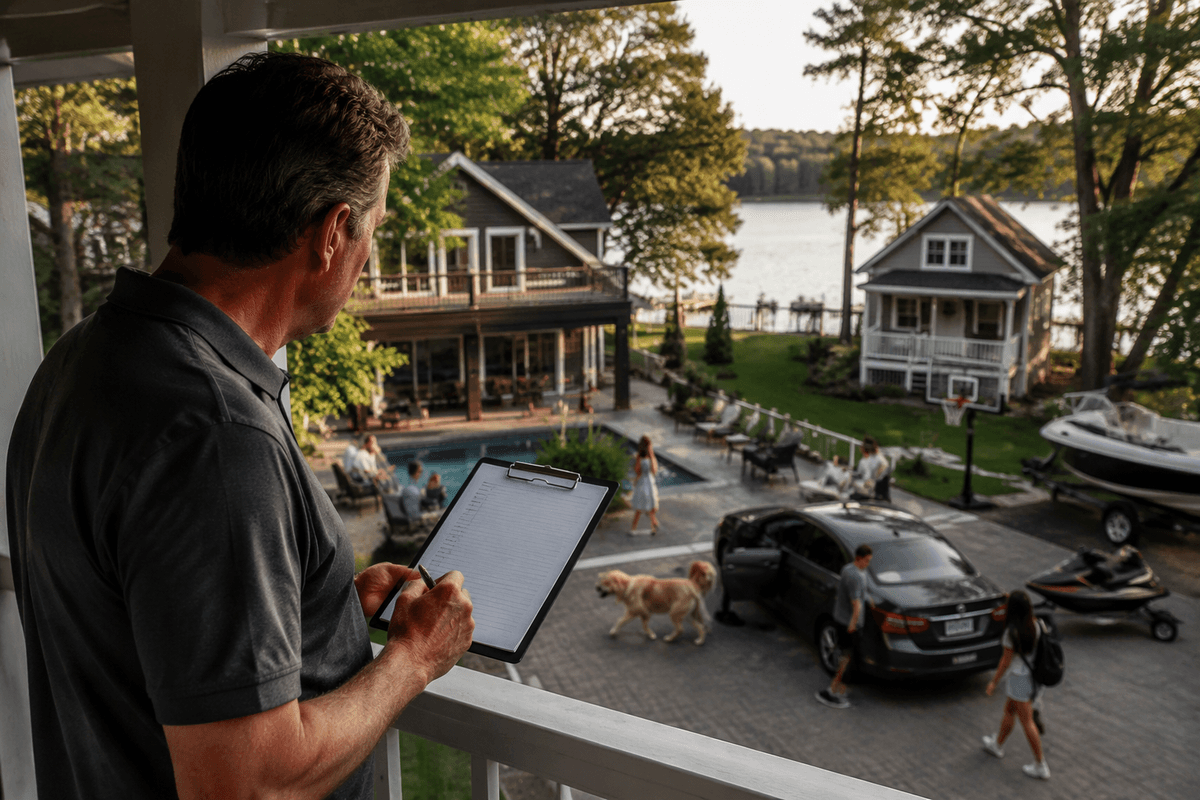
The size of the gap depends less on the policy schedule than on what can realistically generate a claim. A household with teenage drivers, frequent guests, a pool, a large dog, rental property, or recreational equipment may face more severe liability exposure than its basic asset total suggests. Boats, ATVs, and vacant properties can add another layer, especially when they are used by people whose judgment or experience is difficult to control.
Income matters as well. Someone with a high salary, valuable professional skills, or years before retirement may be targeted for future earnings after assets are exhausted. A claim can also involve conduct that standard policies handle differently, such as renting part of the home, hosting large gatherings, or operating a side business. The activity may seem occasional, but the legal and financial consequences do not shrink simply because it was unusual.
That makes a household inventory more useful than a net-worth estimate alone. List vehicles, property, savings, investments, animals, watercraft, rental arrangements, business activities, and regular guests, then ask which policy would respond if each created serious harm. Umbrella insurance may address some of those exposures, but exclusions, required underlying limits, and separate commercial coverage can leave important gaps. The decision becomes clearer when the risks are identified before the premium is compared.
What Umbrella Coverage Adds—and What It Does Not
The value of umbrella coverage appears after the underlying policy has done its part. It can add another layer of liability protection above auto, homeowners, and sometimes other personal policies, helping pay a covered settlement, judgment, or legal defense after the primary limit is exhausted. That extra layer can protect savings, taxable investments, and future income from being drawn into the claim. It may also cover certain situations that standard policies handle less broadly, such as liability involving rental property or incidents away from home.
That protection is not a blank check. Umbrella policies usually require specific underlying liability limits, so increasing the umbrella without adjusting auto or homeowners coverage can create an uncovered gap. Exclusions may apply to intentional harm, business activities, professional services, certain vehicles or watercraft, and some forms of property damage. A household may also need separate coverage for a business, rental operation, or specialized equipment. The policy wording matters more than the headline limit, and defense costs, self-insured amounts, and uncovered claims can change the result. The useful comparison is therefore not simply “premium versus millions of protection,” but how much of the household’s actual exposure the policy would answer after the first layer is gone.
The Premium Looks Small Until Requirements Appear
The quoted premium can look modest until the insurer’s conditions are added. An umbrella policy may require higher auto and homeowners liability limits, which means raising existing coverage before the umbrella becomes effective. That increases the total annual cost and can create a timing problem if one policy renews months before another. Some insurers also require every household vehicle, youthful driver, rental property, or watercraft to be listed and insured through approved underlying policies.
The price can rise further when the household has multiple cars, a teen driver, a pool, rental income, or prior claims. A low quote may also reflect a narrow policy that excludes business activity, certain boats, or incidents involving an unlisted property. Comparing only the umbrella premium therefore gives a distorted result. The better figure is the cost of the full liability structure, including higher primary limits, endorsements, separate policies, and any deductible or self-insured amount. Even then, a cheaper policy may be weaker where the household faces its greatest exposure. The apparent bargain becomes useful only after its requirements and exclusions are placed beside the risks it is meant to cover.
Choosing a Limit Without Chasing False Precision
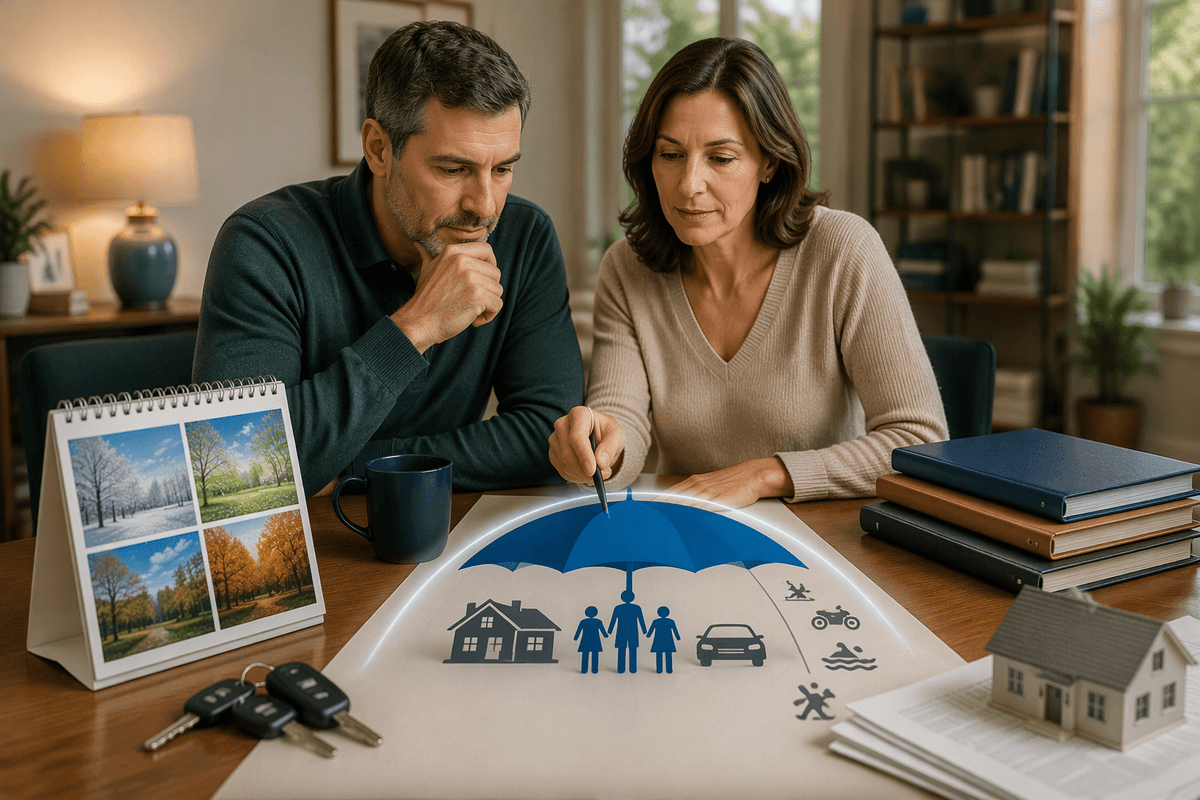
A precise limit is difficult to calculate because assets, income, and claim severity can change before the policy is used. A practical starting point is to compare the household’s exposed assets and several years of future earnings with the liability limits already available. That figure is not a prediction of the next lawsuit; it is a measure of how much remains vulnerable after primary coverage responds.
Rounding to a sensible limit is usually better than treating the estimate as exact. A $1 million policy may be reasonable for one household, while another may need $2 million or more because of rental property, teenage drivers, business activity, or substantial investments. The constraint is cost: higher limits may add premium without solving excluded risks. Recheck the amount after major purchases, income changes, new drivers, or added activities rather than chasing a permanently perfect number.
A Practical Decision: Buy, Delay, or Reassess
The decision can usually be narrowed to three choices. Buy now when exposed assets, future income, or high-severity activities clearly exceed existing liability limits and the full cost remains manageable. Delay when the household has limited assets, few unusual exposures, and more urgent insurance gaps to fix first. Reassess when a new driver, property, boat, rental arrangement, business activity, or major income change could alter the calculation.
Before choosing, request the underlying-limit requirements, exclusions, defense-cost treatment, and total annual premium in writing. A policy should not be purchased merely because the price seems low, or rejected because the limit feels larger than today’s balance sheet. The practical answer may be to strengthen primary coverage now, add an umbrella later, and review the structure whenever the household’s risks materially change.