You budgeted for stability, then visa rules changed
The plan looked clean on paper: steady paycheck, rent that fit the 30% rule, automatic transfers into a cash buffer, and a small, boring investment contribution you could keep running in the background. Then a rule change, a policy shift at the employer, or a slower-than-expected renewal timeline turns “stable” into “conditional” without changing your monthly bills. The money problem isn’t that you miscalculated; it’s that your legal ability to earn can change faster than your obligations can. That mismatch is where budgets fail.
When the visa rules move, your income stops behaving like salary and starts behaving like a scenario. A bonus may not arrive before a status decision, overtime might be off-limits, and switching employers can pause work authorization at the worst time. The same budget line items now carry timing risk, not just dollar risk.
Start with the constraint you can’t ignore
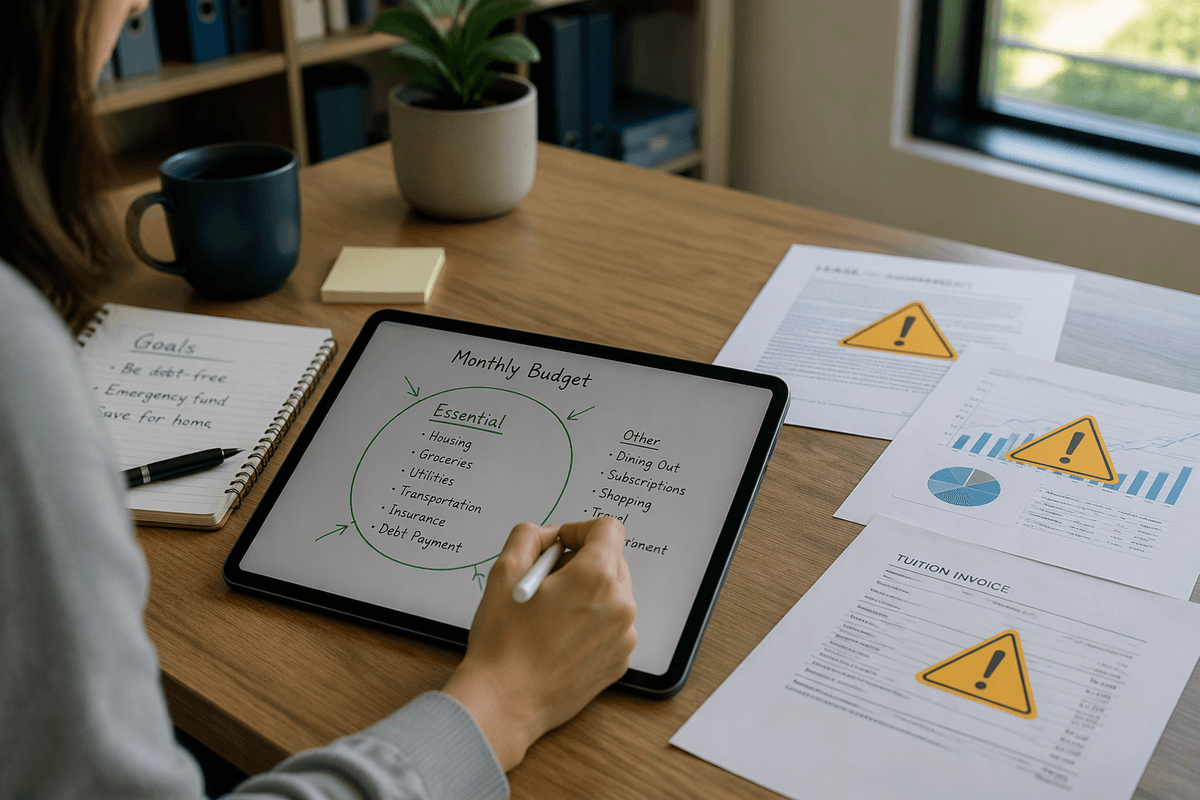
The first thing to lock down isn’t the rent number or the savings rate; it’s the condition under which you’re allowed to keep earning at all. For some people that condition is a hard date (work authorization expiring on a specific day), for others it’s a dependency (only this employer, only these hours, only this role). Once that’s written in plain language, you can price it: how many pay periods disappear if a renewal takes eight extra weeks, or if an employer change forces a pause? That timing risk is the constraint that makes a “reasonable” budget turn into a cash-flow problem overnight.
Then the budget gets rebuilt around the narrowest point. Fixed obligations—lease, loan payments, insurance premiums—have to fit inside the income you can defend even in an interruption. If the only dependable asset is liquidity, treat it like a bill: a minimum cash buffer sized to your burn rate and your most likely delay window. Anything that requires steady authorization to be safe—long leases, aggressive investing, prepaying tuition on credit—goes on probation until the constraint loosens.
Build three income paths before committing
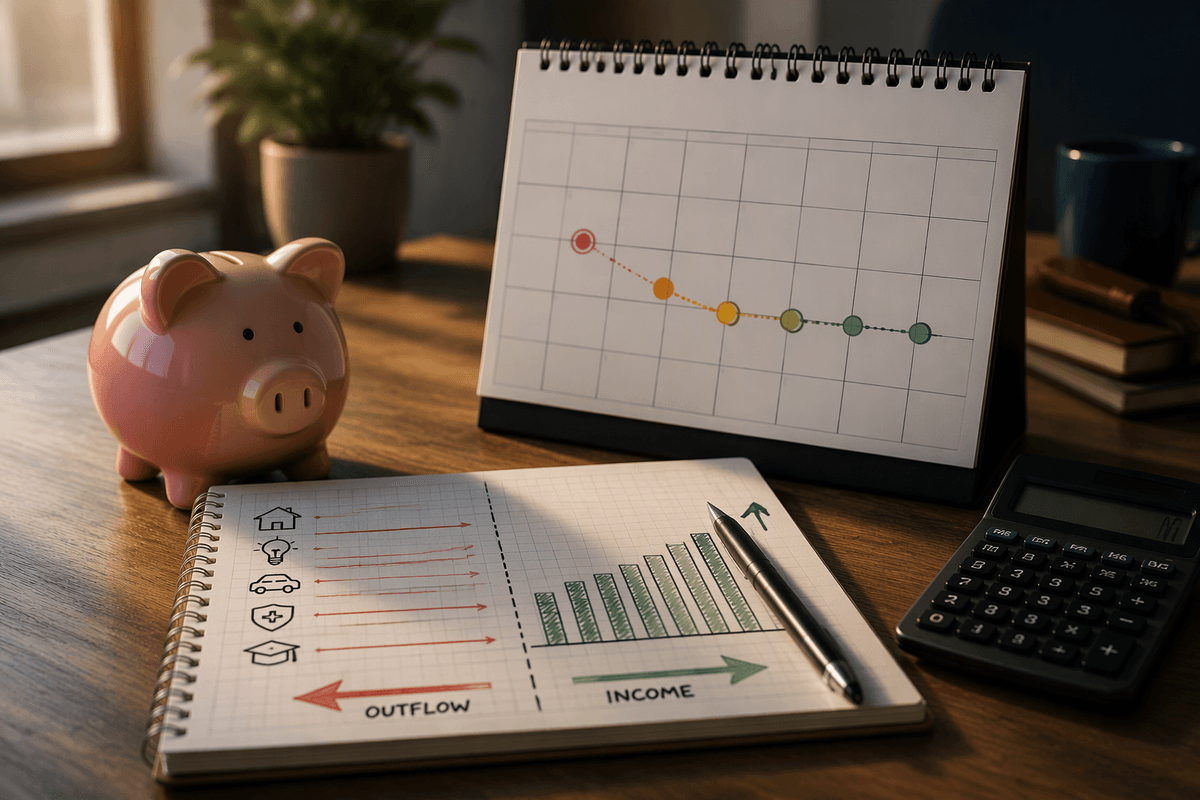
Once the constraint is written down, the next practical move is to stop treating “monthly income” as one figure and sketch three paths you can actually live through. Path A is uninterrupted authorization: base pay after tax, minus any deductions that don’t stop when you’re anxious (health premiums, retirement contributions). Path B is a pause scenario: the same job on paper, but a gap of 4–10 weeks where payroll is zero and the only “income” is what you already have in cash. Path C is a forced change: new employer, reduced hours, or a role shift that resets timing and makes bonuses, equity vesting, and reimbursements irrelevant for months.
Commitments only graduate out of probation when they clear all three paths. If rent, debt payments, and minimum savings only fit in Path A, then you’re not budgeting—you’re betting on processing times and HR speed. The discipline is boring: size fixed costs to Path B, treat Path A’s surplus as optional, and reserve Path C for decisions you can reverse without fees, penalties, or a credit hit.
Choose commitments that survive a bad month
The pressure point shows up when the month isn’t catastrophic, just messy: one delayed payroll cycle, an unpaid week between employers, a renewal receipt that doesn’t arrive on time. In that “bad month,” the commitments that hurt aren’t the big dreams, they’re the small contracts that pretend to be harmless—12‑month phone plans with device financing, annual subscriptions, gym memberships with exit fees, “0%” installment plans that still demand on-time payments. The review lens is simple: if cash flow drops to Path B for 30–45 days, which bills keep charging, and which ones can be paused without penalties or credit damage?
That’s where commitment design matters. Prefer month-to-month housing when feasible, or negotiate lease break language before you need it; keep car decisions biased toward lower fixed payments over nicer terms; avoid locking cash into nonrefundable deposits right before an authorization milestone. Auto-investing and extra debt payments can still happen, but treat them as throttles, not promises—set them to amounts you can sustain even while rebuilding a buffer.
When the bad month is survivable on paper, the rest of the plan stops feeling like a wager on processing times.
Work benefits look safe until you switch jobs
The next surprise usually isn’t payroll; it’s everything attached to payroll. A benefits portal makes it feel like coverage is permanent—health insurance cards, an HSA balance, a commuter account, a 401(k) match ticking along. Then a job change forces the real timing to show up. There’s the last day of coverage, the first day the new plan starts, and the quiet gap in between that HR can’t always “fix” quickly. If the switch is driven by visa timing, that gap can land exactly when you’re least willing to take risks, and even one urgent-care visit turns into a cash decision.
So the review shifts from “Do I have benefits?” to “When are they active, and what happens mid-transition?” COBRA can be expensive, short-term plans may not be available or useful for everyone, and some employers start coverage on day one while others start it weeks later. Retirement matching is similar: vesting schedules reset, probation periods delay eligibility, and a layoff or forced switch can turn “free money” into money you never actually receive. Before committing to a new role, it’s worth pricing the benefits gap like a bill and treating it as part of Path B, not a rare edge case.
Side-income workarounds create a second constraint
After you’ve priced the benefits gap, the next instinct is predictable: patch cash flow with “something small” on the side. A few freelance projects, tutoring, food delivery, a paid newsletter—anything that smooths Path B without touching the main job. The friction is that side money isn’t just a tax problem or a time problem. For many temporary statuses, it’s a permission problem, and the penalty for getting it wrong isn’t a fee; it’s a status complication that shows up right when you need renewals to be boring.
Even when a workaround is technically allowed, it can create a second constraint that behaves like a hidden bill. Hours spent earning extra cash can reduce your capacity to job-search fast during a forced change, and income that looks “flexible” can be slow to access—platform payout delays, clients who pay net-30, or funds held for disputes. That’s how a plan meant to add cushion quietly increases timing risk. In the review, side income only counts if it’s both compliant and collectible inside the same 2–4 week window you’re trying to protect.
Set tripwires for renewal delays and job loss
Now the plan needs alarms, not optimism. Pick two dates that matter more than the expiration date: the day you expect a receipt/approval to arrive, and the day a missed paycheck would force you to borrow. If the first date slips by even a week, that’s a tripwire to freeze every optional transfer (extra debt payments, investing, travel, gifts) and stop any purchase that creates a new monthly bill. It feels premature, but the cost of waiting is usually fees and rushed choices.
Set one more trigger tied to job risk: if severance is unclear or the employer hints at changes, move one month of expenses into a plain, accessible cash buffer and pre-plan the “minimum month” budget. The goal isn’t certainty; it’s making the first 30 days predictable.